TL;DR: What You Need to Know
- Australia has four main tax residency tests: resides, domicile, 183-day, and Commonwealth superannuation.
- You do not need to pass all four tests. One test can be enough to establish residency.
- Spending 183 days in Australia does not automatically settle every residency question.
- Australian residents are generally taxed on worldwide income. Foreign residents are generally taxed on Australian-source income.
- Leaving Australia can trigger CGT event I1 on certain assets, including shares and cryptocurrency.
- Two countries can treat you as a tax resident at the same time. A double tax agreement may affect how they tax your income.
- From 1 July 2026, the resident tax rate on income between $18,200 and $45,000 is 15%.
- Keep records of your travel, home, employment, family arrangements, and the date your circumstances changed.
Moving to Australia, leaving the country, or working overseas can change your tax obligations. But your tax residency does not depend on your passport or the number of days you spend in one country alone. The Australian Taxation Office (ATO) considers where you live, your home, your work, your family ties, and your plans.
Understanding tax residency is important before you lodge a tax return, complete a bank declaration, sell investments, or move overseas. Your status can affect which income Australia taxes and whether leaving the country triggers capital gains tax.
This guide explains the four Australian tax residency tests, how to check your status, what evidence to keep, and how the rules apply to expats, digital nomads, and people returning to Australia. It also covers dual residency, superannuation, residency certificates, and important tax changes for 2026 and 2027.
What Does Tax Residency Mean in Australia?
The tax residency meaning is whether a person is treated as a resident under a country’s tax laws. In Australia, the ATO uses specific legal tests to decide whether you are an Australian resident for tax purposes or a foreign resident.
Your tax residency status can affect:
- Whether you need to report income earned overseas.
- How Australia taxes income earned in Australia.
- Your tax return obligations when you arrive or leave.
- Capital gains tax when you sell assets or stop being an Australian tax resident.
- Your tax position if another country also considers you a resident.
Tax residency Australia is worked out using the legal tests and your circumstances for the relevant period. The Australian income year usually runs from 1 July to 30 June.
You can become or stop being an Australian tax resident during a financial year. If your residency changes, your tax return needs to reflect the relevant dates and rules.
Unsure how your tax residency status affects your Australian tax return? ISM Accountants & Advisors can help you understand your tax obligations, report the right income and prepare your tax return based on your circumstances. Contact our team for professional tax return services.
What Are the Four Australian Tax Residency Tests?
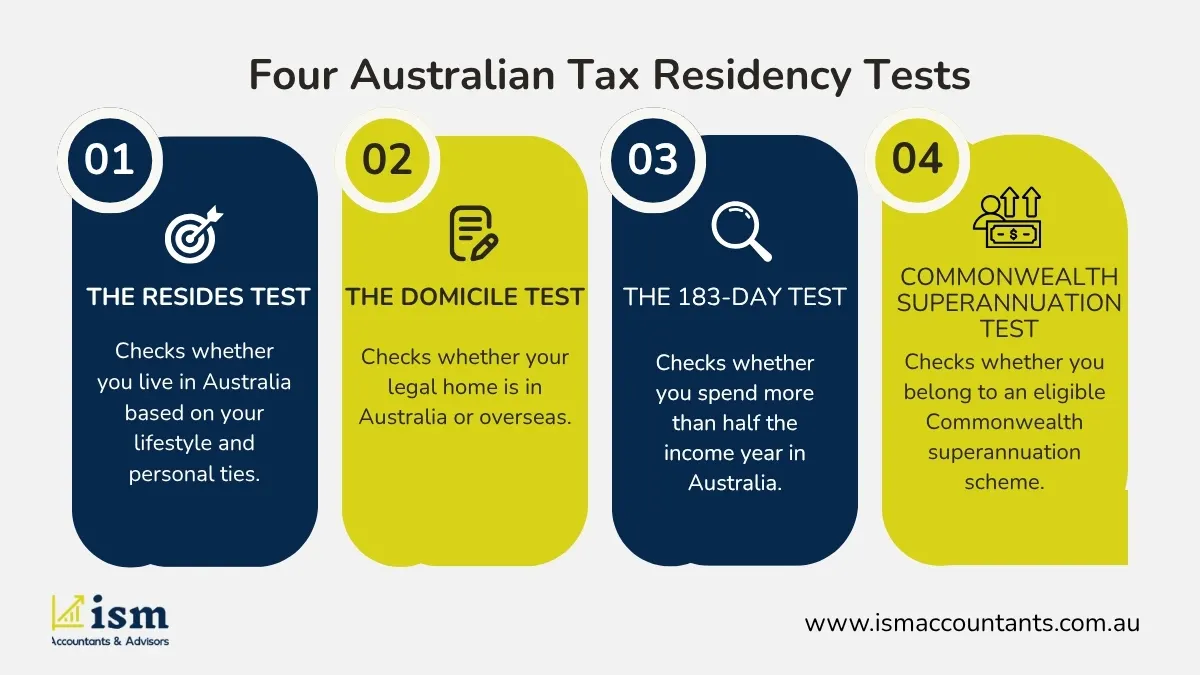
Australia has four main individual tax residency tests:
- The resides test.
- The domicile test.
- The 183-day test.
- The Commonwealth superannuation test.
You do not need to pass all four. Meeting one test can be enough to establish Australian tax residency, depending on the test and your circumstances.
1. The Resides Test
The resides test asks whether you live in Australia in the ordinary sense of the word. The ATO looks at the overall pattern of your life, not one detail in isolation.
Factors include:
- How long you stay in Australia and how often you return.
- Whether you have a settled home or temporary accommodation.
- Where your spouse and children live.
- Where you work or run a business.
- Your social and financial connections.
- Whether your actions show that Australia is your home.
For example, a person who arrives in Australia, rents a long-term home, starts a job, and moves their family may be establishing a life in Australia. This can support Australian tax residency even if they have not spent 183 days in the country.
The ATO also refers to a practical six-month rule of thumb. Spending six months or more continuously in Australia, working in one job for most of that time, and living in the same place can point towards residency. This is not a separate legal test or an automatic decision.
2. The Domicile Test
Domicile is a legal concept. It is not the same as citizenship, your current address, or the country where you own property.
If your domicile is in Australia, you can remain an Australian tax resident unless the ATO is satisfied that your permanent place of abode is outside Australia.
The ATO considers factors such as:
- How long you plan to live overseas and how long you actually stay.
- Whether you have established a home in another country.
- Whether you intend to return to Australia.
- How stable your overseas living arrangements are.
- Whether a home remains available to you in Australia.
- The strength of your personal and financial ties in each country.
Is there a two-year rule? There is no fixed two-year cutoff that automatically determines tax residency. ATO guidance uses a broad rule of thumb: an intended absence of less than two years is unlikely, by itself, to establish a permanent place of abode overseas. An absence of two years or more still needs to be assessed using all the facts.
Example: leaving Australia for 18 months
Daniel moves overseas for an 18-month work assignment. His spouse and children remain in the Australian family home, and he plans to return when the assignment ends. These facts may support continued Australian tax residency, even though he works and lives overseas during the assignment.
A different result may apply if Daniel establishes a lasting home overseas and moves his family and personal life there.
3. The 183-Day Test
The 183-day test considers whether you are physically present in Australia for more than half of the income year.
However, the 183-day rule does not decide every residency case. Under this test, you may be treated as an Australian tax resident if you are in Australia for more than half of the income year, unless your usual place of abode is outside Australia and you do not intend to take up residence in Australia.
Consider two examples:
- A visitor spends an extended period in Australia but keeps their usual home overseas and does not intend to take up residence. The exception may apply.
- A person arrives to settle in Australia, establishes a home, and stays for much of the income year. The 183-day test and the other tests need to be considered.
You can become an Australian tax resident without spending 183 days in Australia. Likewise, spending more than 183 days here does not mean you should ignore the legal exception.
4. The Commonwealth Superannuation Test
This test mainly applies to certain Australian Government employees who are members of the Public Sector Superannuation Scheme (PSS) or Commonwealth Superannuation Scheme (CSS), as well as eligible spouses and children covered by the rules.
It does not apply to everyone with an Australian superannuation account. Having an ordinary super fund does not, by itself, make you an Australian tax resident under this test.
If you work for the Australian Government overseas or are covered by a relevant Commonwealth superannuation scheme, check the specific rules that apply to you.
What Are the Australian Tax Residency Requirements?
The tax residency requirements depend on which legal test applies to your circumstances. There is no single checklist that determines every case.
Start by answering these questions:
- Where do you live? Consider whether your home is in Australia or overseas and whether your arrangements are temporary or settled.
- What are your plans? Think about whether you moved overseas for a defined assignment, intend to return, or have established a lasting home elsewhere. Your intentions matter, but your actions matter too.
- What ties remain in Australia? Consider your available home, family, employment, business interests, and personal connections.
- How have your circumstances changed? A decision made when you first leave Australia may need to be reviewed if your plans change, your overseas stay becomes permanent, or your family moves.
Do the tests support the same conclusion? One test may establish residency. If the tests point in different directions, you may need a detailed review of the law and your evidence.
How Do I Determine If I Am a Tax Resident?
To determine your tax residency status:
- Write down your Australian arrival and departure dates.
- List where you lived, worked, and kept your main home.
- Record where your spouse and dependants lived.
- Review the four tests against those facts.
- Gather evidence that supports your conclusion.
- Seek professional advice if your situation involves multiple countries, Australian property, or a change in plans.
The ATO provides two decision tools on its Work out your residency status for tax purposes page. Use the “Are you a resident?” tool if you have come to Australia to work or live, or the leaving-Australia tool if you are moving overseas.
These tools are a useful starting point, but a complex case involving multiple countries, a home in Australia, or valuable investments can require a closer review.
What Documents Can Prove Australian Tax Residency or Non-Residency?
No single document proves tax residency in every situation. The useful evidence depends on the test and the period being reviewed.
Keep records such as:
- Passport stamps, flight records, and travel history.
- Lease agreements, property documents, and utility bills.
- Employment contracts, payslips, and overseas assignment letters.
- Evidence of where your spouse and dependants lived.
- Records showing whether an Australian home remained available to you.
- Overseas tax returns or certificates of tax residence.
- Documents showing when you moved and how your living arrangements changed.
How do you prove that you are no longer an Australian tax resident? You need evidence supporting the conclusion that you meet the rules for foreign residency. There is no universal form that automatically ends Australian tax residency.
For example, if you moved overseas to establish a permanent home, your overseas lease, employment contract, travel records, and family arrangements may help explain the move. A statement that you intended to leave permanently is less persuasive if your actual arrangements tell a different story.
What Is the Difference Between Tax Residency and Immigration Residency?
Tax residency determines how Australia taxes your income and certain assets. Immigration residency relates to your visa and your legal right to enter, remain, or live in Australia.
The two are separate: a person can hold a temporary visa and still be an Australian tax resident, while an Australian citizen can be a foreign resident for tax purposes. The ATO’s tax residency guide explains the tax rules.
Does Keeping a Home in Australia Affect Tax Residency?
It can. The ATO considers whether a home remains available to you in Australia and whether you have established a home overseas.
Owning an Australian property does not automatically make you an Australian tax resident. A property rented to tenants and unavailable for your personal use can be different from a home you keep available for your return.
Likewise, buying or renting a home overseas does not automatically end Australian tax residency. The wider pattern of your life matters.
What Happens When You Return to Australia?
Your tax residency can change again when you return. If you come back to settle, move into a home, and start a long-term job, your circumstances may support a change to Australian tax residency.
A short visit for a holiday or family event is different from a move to re-establish your life in Australia.
Keep records of your return date, accommodation, employment, and family arrangements. If you were a foreign resident before returning, review your tax position for the income year in which you came back.
Recommended Read: Superannuation for Working Holiday Visa Holders in Perth
What If I Arrive in Australia to Study?
A student visa does not automatically make you a foreign resident for tax purposes. The ATO considers your circumstances under the residency tests, including whether you live in Australia and the nature of your stay.
Example: a student on a long course
Maya arrives from overseas to study a three-year degree. She rents a home in Australia, works part-time, and builds her daily life here. These facts can support Australian tax residency under the resides test, even though she holds a temporary student visa.
Her immigration status and tax residency are separate questions. She may also qualify as a temporary resident for certain tax rules, which can change how some foreign income and capital gains are treated.
Tax Residency for Digital Nomads Working Overseas
Digital nomads often work remotely while moving between countries. Working online for an Australian business does not automatically make you an Australian tax resident. Working for a foreign employer does not automatically make you a foreign resident either.
Your status depends on the residency tests and the facts of your life. Factors include how long you stay in each country, where you establish a home, whether you keep an Australian home available, and where your family and personal ties remain.
Digital nomads should review four key tax issues.
- Overseas income: Australian residents are generally taxed on worldwide income, subject to applicable rules and exemptions. Foreign residents are generally taxed on Australian-source income. Remote work can require careful analysis of where the work is performed, your residency status, and any applicable tax treaty.
- Tax returns: If your residency changes during the financial year, your tax return needs to reflect the change. Leaving Australia does not automatically remove every Australian tax return obligation.
- Capital gains tax: If you cease Australian tax residency, CGT event I1 can apply to certain assets you own, even if you have not sold them. Shares, crypto assets, and other investments need to be reviewed before you leave.
- Superannuation: Your tax residency and your eligibility to access super are separate questions. Leaving Australia does not automatically allow you to withdraw your super. DASP eligibility depends on your visa and personal circumstances.
Digital nomads should keep travel records, work contracts, details of their homes, and evidence of where they performed their work. If you move frequently or have ties to several countries, get advice before making a residency declaration.
What Happens to Your Tax Obligations When You Move Overseas?
Moving overseas can affect income tax, capital gains tax, bank declarations, and tax return obligations. The changes depend on when your residency ends and which assets and income you hold.
An Australian tax resident is generally taxed on worldwide income, while a foreign resident is generally taxed on Australian-source income. Foreign residents also have different tax rates and may not qualify for the tax-free threshold or certain concessions.
The details depend on your circumstances and the type of income involved.
For tax rates, thresholds, and a side-by-side comparison, read our guide to Resident vs Non-Resident Tax in Australia.
Do You Pay Australian Tax on Overseas Income as a Non-Resident?
Generally, no. A foreign resident pays Australian tax on income from Australian sources, such as wages for work done in Australia or rent from Australian property. Income earned entirely overseas is generally outside the Australian income tax net for a foreign resident.
If you are still an Australian resident under the residency tests, your overseas income is generally taxable in Australia too. Special rules can apply to temporary residents and certain types of income.
How Does Tax Residency Affect Australian Tax Returns?
If your residency changes during a financial year, your tax return needs to reflect the relevant dates and status. You may need to report when you became or stopped being an Australian resident and provide information about the months you were a resident.
Part-year tax-free threshold: a worked example
The ATO’s current guidance gives two components for the part-year tax-free threshold: a base amount of $13,464 and a pro-rata share of $4,736, based on the number of months you were an Australian resident during the income year.
If you were an Australian tax resident for six months:
- Base amount: $13,464
- Pro-rata amount: $4,736 × 6 ÷ 12 = $2,368
- Total part-year threshold: $15,832
The calculation can apply when you become an Australian resident or stop being one during the year. The ATO uses the number of months you were a resident, including the month you arrived. Confirm the current rules when lodging your return.
For tax return help, visit our Australian taxation services page.
What Is CGT Event I1 When You Leave Australia?
CGT event I1 is one of the most important tax issues to review when you cease being an Australian tax resident.
Under this rule, you are generally treated as having disposed of certain capital gains tax (CGT) assets at their market value when you stop being an Australian resident. This is called a deemed disposal: the tax law treats you as if you sold the asset, even when you have not actually sold it.
The rule generally excludes taxable Australian property. This term covers certain Australian assets, including Australian real estate and some business-related assets, that remain within Australia’s CGT rules for foreign residents.
Assets that may need to be reviewed include shares, cryptocurrency, and other investments that are not taxable Australian property.
Worked example: Emma bought Bitcoin for $10,000 while she was an Australian tax resident. When she ceased Australian tax residency, the Bitcoin was worth $22,000. If CGT event I1 applies, the initial capital gain is $12,000 before losses and other adjustments.
If Emma held the asset for more than 12 months, the 50% CGT discount may apply under the rules relevant to that event. The final taxable gain depends on her circumstances and the law in force at the time.
An individual can choose to disregard the gain or loss at departure. If they make this choice, the relevant assets are generally treated as taxable Australian property until they are disposed of or the individual becomes an Australian resident again. This can defer the tax outcome rather than remove it.
Review your assets, market values, cost bases, and potential tax bill before you leave.
How Does Tax Residency Affect Australian Property?
Foreign residents should pay particular attention to Australian real estate.
For relevant property contracts entered into on or after 1 January 2025, the foreign resident capital gains withholding rate increased to 15%, and the previous $750,000 threshold was removed. The withholding can therefore apply to property transactions below the former threshold.
The amount withheld is generally a payment towards the seller’s potential tax liability, not necessarily the final tax owed. Eligible Australian resident sellers generally need an ATO clearance certificate to avoid withholding under the relevant rules.
Foreign residents generally cannot claim the main residence exemption for Australian residential property sold after 30 June 2020, even if the property was their home for part of the ownership period.
A limited life-events exception can apply if the specific requirements are met. These include conditions relating to the period of foreign residency and qualifying events such as certain terminal medical conditions, a spouse or child’s death, or a relationship breakdown.
How Does Tax Residency Affect Superannuation and DASP?
Your tax residency and your eligibility to withdraw superannuation are separate matters.
A Departing Australia Superannuation Payment (DASP) is generally available to eligible temporary residents who worked in Australia, have left the country, and whose eligible temporary visa has expired or been cancelled. Australian and New Zealand citizens and Australian permanent residents are not eligible for DASP simply because they move overseas.
DASP withholding rates depend on the payment component and visa category:
- 35% on the taxed element of the taxable component for ordinary DASP payments.
- 45% on the untaxed element of the taxable component for ordinary DASP payments.
- 65% on the taxable component for working holiday makers.
The tax-free component is generally paid without DASP withholding tax.
Becoming a foreign resident for tax purposes does not, by itself, make you eligible for DASP.
For step-by-step information, read our guide to claiming your super after leaving Australia through DASP.
Leaving Australia and unsure how to claim your super? ISM Accountants & Advisors can help you understand the Departing Australia Superannuation Payment (DASP) process and the tax implications of withdrawing your eligible super. Visit our Departing Australia Superannuation Service to learn more.
Can You Be a Tax Resident of Australia and Another Country at the Same Time?
Yes. Two countries can treat you as a tax resident under their own domestic laws. This is known as dual tax residency.
For example, you might move overseas for work but retain strong ties to Australia. Australia may consider you a resident under its domestic tests, while the other country may also treat you as a resident under its own rules.
A double tax agreement (DTA), where one applies, can help resolve competing claims for treaty purposes. Depending on the agreement, its tie-breaker rules may consider:
- Where you have a permanent home.
- Where your personal and economic interests are closer.
- Where you usually live.
- Your nationality, if the earlier tests do not resolve the issue.
A tax treaty does not simply erase Australian domestic law. It affects how the agreement applies to your circumstances and the countries’ taxing rights.
If you pay tax on the same income in two countries, you may be eligible for a foreign income tax offset in Australia. This depends on the income being included in your Australian assessable income and the rules for the offset. A tax treaty can also change which country has taxing rights over certain income.
Tax Residency Details Australia: What to Gather Before You Act
If you need to confirm your tax position before moving, selling assets, or completing a bank form, gather the information that helps explain your circumstances.
Prepare:
- Your arrival and departure dates.
- The addresses and availability of homes in Australia and overseas.
- Your employment details and where you perform your work.
- The countries where your spouse and dependants live.
- Details of Australian property, investments, and superannuation.
- Overseas tax returns or tax residence certificates.
- Any bank or foreign tax authority request asking you to confirm your status.
These details help you assess the residency tests and prepare accurate declarations. They also make it easier for an accountant to identify the issues that need closer review.
How Can You Obtain an Australian Tax Residency Certificate?
An overseas tax authority, bank, or other organisation may ask for official proof that you are an Australian tax resident. The ATO provides a process for individuals to request a certificate of residency or have an overseas tax relief form certified.
You can use Form NAT 75441, Certificate of Residency and Certification of Overseas Tax Relief — Request Form for Individuals. Read the instructions and submit the form with the required details and supporting documents.
The ATO says you should receive your certificate or certified form within 28 days. Apply well before a foreign tax or filing deadline in case the ATO needs extra information.
A certificate does not replace the residency rules. You must meet the ATO’s requirements, and you may still need to consider a double tax agreement if another country also treats you as a resident.
What Has Changed in 2026?
2026–27 Resident Tax Rates
From 1 July 2026, the resident tax rate on income between $18,200 and $45,000 falls from 16% to 15%. This rate applies to that income band, not to all of a taxpayer’s income.
The change is legislated in the Treasury Laws Amendment (More Cost of Living Relief) Act 2025. Check the ATO’s individual income tax rates when preparing a return for the relevant income year.
CGT Changes From 1 July 2027
The Treasury Laws Amendment (Tax Reform No. 1) Act 2026 received Royal Assent on 26 June 2026. The changes are enacted, with key CGT adjustments applying from 1 July 2027.
For eligible resident individuals and trusts, the existing 50% CGT discount is replaced by a system using cost-base indexation for relevant gains. The Act also introduces a minimum tax mechanism for certain capital gains. Foreign and temporary residents are excluded from the new indexation rules.
The legislation has detailed transitional rules, including how assets held before 1 July 2027 are treated. The result depends on the asset, the CGT event, and the taxpayer’s status. If you are planning to leave Australia or sell investments, get advice before assuming the new system will apply to your situation in a particular way.
Is the Proposed 45-Day Residency Rule Law?
No. Treasury consulted on a proposal to modernise Australia’s individual tax residency framework. The proposed model included a primary 183-day test and secondary tests that discussed a 45-day threshold in certain circumstances.
Those proposed tests did not replace the existing four individual residency tests. As of October 2026, you should not use a proposed 45-day threshold as if it were current law.
When Should You Consult an Australian Tax Accountant?
Professional advice can be useful if:
- You are moving to or from Australia and your residency status is unclear.
- You are leaving Australia but keeping a home, investments, or business interests here.
- You work remotely overseas or move between countries as a digital nomad.
- Your spouse or children live in a different country from you.
- You may be a tax resident of two countries.
- You plan to sell Australian property after moving overseas.
- You hold shares, cryptocurrency, or other assets that may be affected by CGT event I1.
- A bank or overseas tax authority has asked for a residency declaration or certificate.
- Your residency changed part-way through the financial year.
- You need to correct an earlier return or respond to an ATO enquiry.
An accountant should review the facts, apply the relevant tests, and explain which records support the conclusion. For international matters, look for experience with cross-border tax, CGT, and double tax agreements.
How to Choose an Australian Tax Residency Accountant
Before engaging an accountant, ask:
- Have you handled Australian tax residency cases involving overseas moves?
- Can you assess the four tests and explain the reasoning?
- Can you review CGT event I1 and assets affected by a change in residency?
- Do you understand double tax agreements and foreign income tax offsets?
- Can you help with amended returns or ATO enquiries?
- What records do you need, what will the work cost, and what is included?
Check the practitioner’s registration. In Australia, verify that anyone providing tax agent services for a fee is registered with the Tax Practitioners Board (TPB), where required. Use the TPB Public Register to check registration details.
If you also need company setup advice, keep that question separate from your personal tax residency assessment. Our guide to registering a company in Australia as a non-resident covers company formation and compliance. A company’s director-residency requirements are not the same as an individual’s tax residency test.
For help with your own tax position, contact ISM Accountants & Advisors.
What Happens If the ATO Says You Reported Your Tax Residency Incorrectly?
If the ATO disagrees with the residency status reported in your tax return, it can review your circumstances and amend your assessment where the law allows.
You may need to provide travel, employment, housing, and family records, explain when your residency changed, or correct a previous return. If the revised assessment shows more tax is due, interest and penalties can apply depending on the circumstances.
A genuine mistake is not necessarily treated the same as a deliberate or reckless misstatement. Your records and how you respond can matter.
Do not ignore an ATO letter about residency. Read the request carefully, note any deadline, and obtain advice if you disagree with the ATO’s position.
If you believe an assessment is wrong, ask a registered tax agent about the available review or objection process. Check the deadline stated in your assessment or notice.
Final Thoughts
Australian tax residency depends on your circumstances, not just your passport, visa, or time spent in the country. The four tests provide the legal framework, while your home, work, family ties, and plans help determine how those tests apply.
If you are leaving Australia, returning, working remotely overseas, or holding investments across borders, review your residency position before making a tax decision. Pay particular attention to CGT event I1, dual residency, superannuation, and the records that support your conclusion.
For a closer look at how tax rates and obligations differ after you establish your status, read our guide to how tax rates differ for Australian residents and foreign residents.
ISM Accountants & Advisors can help you understand the rules, review your evidence, and plan your next steps. Contact our team to discuss your circumstances.
Frequently Asked Questions About Australian Tax Residency
What is the meaning of a tax resident?
A tax resident is someone treated as a resident under a country’s tax laws. In Australia, the ATO applies four main tests to determine whether a person is an Australian resident for tax purposes. This status affects which income and tax obligations apply.
How do I determine if I am a tax resident?
Review your circumstances against the four Australian tax residency tests. Consider where you live, your domicile, the time you spend in Australia, and whether the Commonwealth superannuation test applies. Start with the ATO’s residency decision tools.
Is the 183-day rule enough to determine Australian tax residency?
No. The 183-day test is only one of the four tests. Its exception can apply if your usual place of abode is outside Australia and you do not intend to take up residence in Australia. Your circumstances and the other tests must also be considered where relevant.
Can I be an Australian tax resident while living overseas?
Yes. You can remain an Australian tax resident while living overseas if the relevant tests support that outcome. Your domicile, overseas home, intentions, and ongoing ties can be relevant. Living abroad does not automatically end Australian tax residency.
Does Australian citizenship or permanent residency automatically make me an Australian tax resident?
No. Citizenship and immigration status are different from tax residency. The ATO applies the tax residency tests to your circumstances, including your home and living arrangements. Citizenship or domicile can be relevant to some questions, but neither replaces the tests.
Why is my bank asking for tax residency in Australia?
Banks may need your tax residence and tax identification number to meet international reporting obligations under frameworks such as the Common Reporting Standard and FATCA. A bank’s request does not decide your status. Give accurate information based on your circumstances and the relevant rules.
How do I prove that I am no longer an Australian tax resident?
Keep evidence of your move, overseas home, employment, travel dates, family arrangements, and other changes. No single document automatically ends tax residency. Your evidence needs to support the conclusion under the relevant test.
Do I pay Australian tax on overseas income if I am a non-resident?
Generally, no. A foreign resident pays Australian tax on income from Australian sources, such as wages for work done in Australia or rent from Australian property. Income earned entirely overseas is generally outside the Australian income tax net. If you remain an Australian tax resident, your overseas income is generally taxable in Australia, subject to special rules.